From extracurricular activities at school, to music, through the gym and swimming pool: here are which activities allow you to recover part of the expense in your tax return, what the limits are and how to pay so as not to lose the benefit
The school year begins and the children’s afternoon classes begin. In recent weeks, families are enrolling children and teenagers in sporting and creative activities and it is good to pay attention to how you pay and what you keep, because various expenses can then be deducted in your tax return.
The fees and activities organized by the school attended by the children fall into a single large expenditure chapter, with a maximum ceiling of one thousand euros per year for each child and a deduction that can reach up to 190 euros. Within this limit there are not only school taxes and contributions, but also extra courses such as foreign languages, theatre, IT or other laboratories, under a specific condition: they must have been approved or organized directly by the school bodies, not simply proposed by an external body that rents the school spaces. Anyone who pays for this type of course will therefore have to obtain, together with the receipt, a copy of the resolution certifying their connection with the institute. Even before and after-school services, for those who need to drop off their children before lessons or pick them up later, fall within this same spending ceiling.
Children’s sports: up to 210 euros of deductible expenses
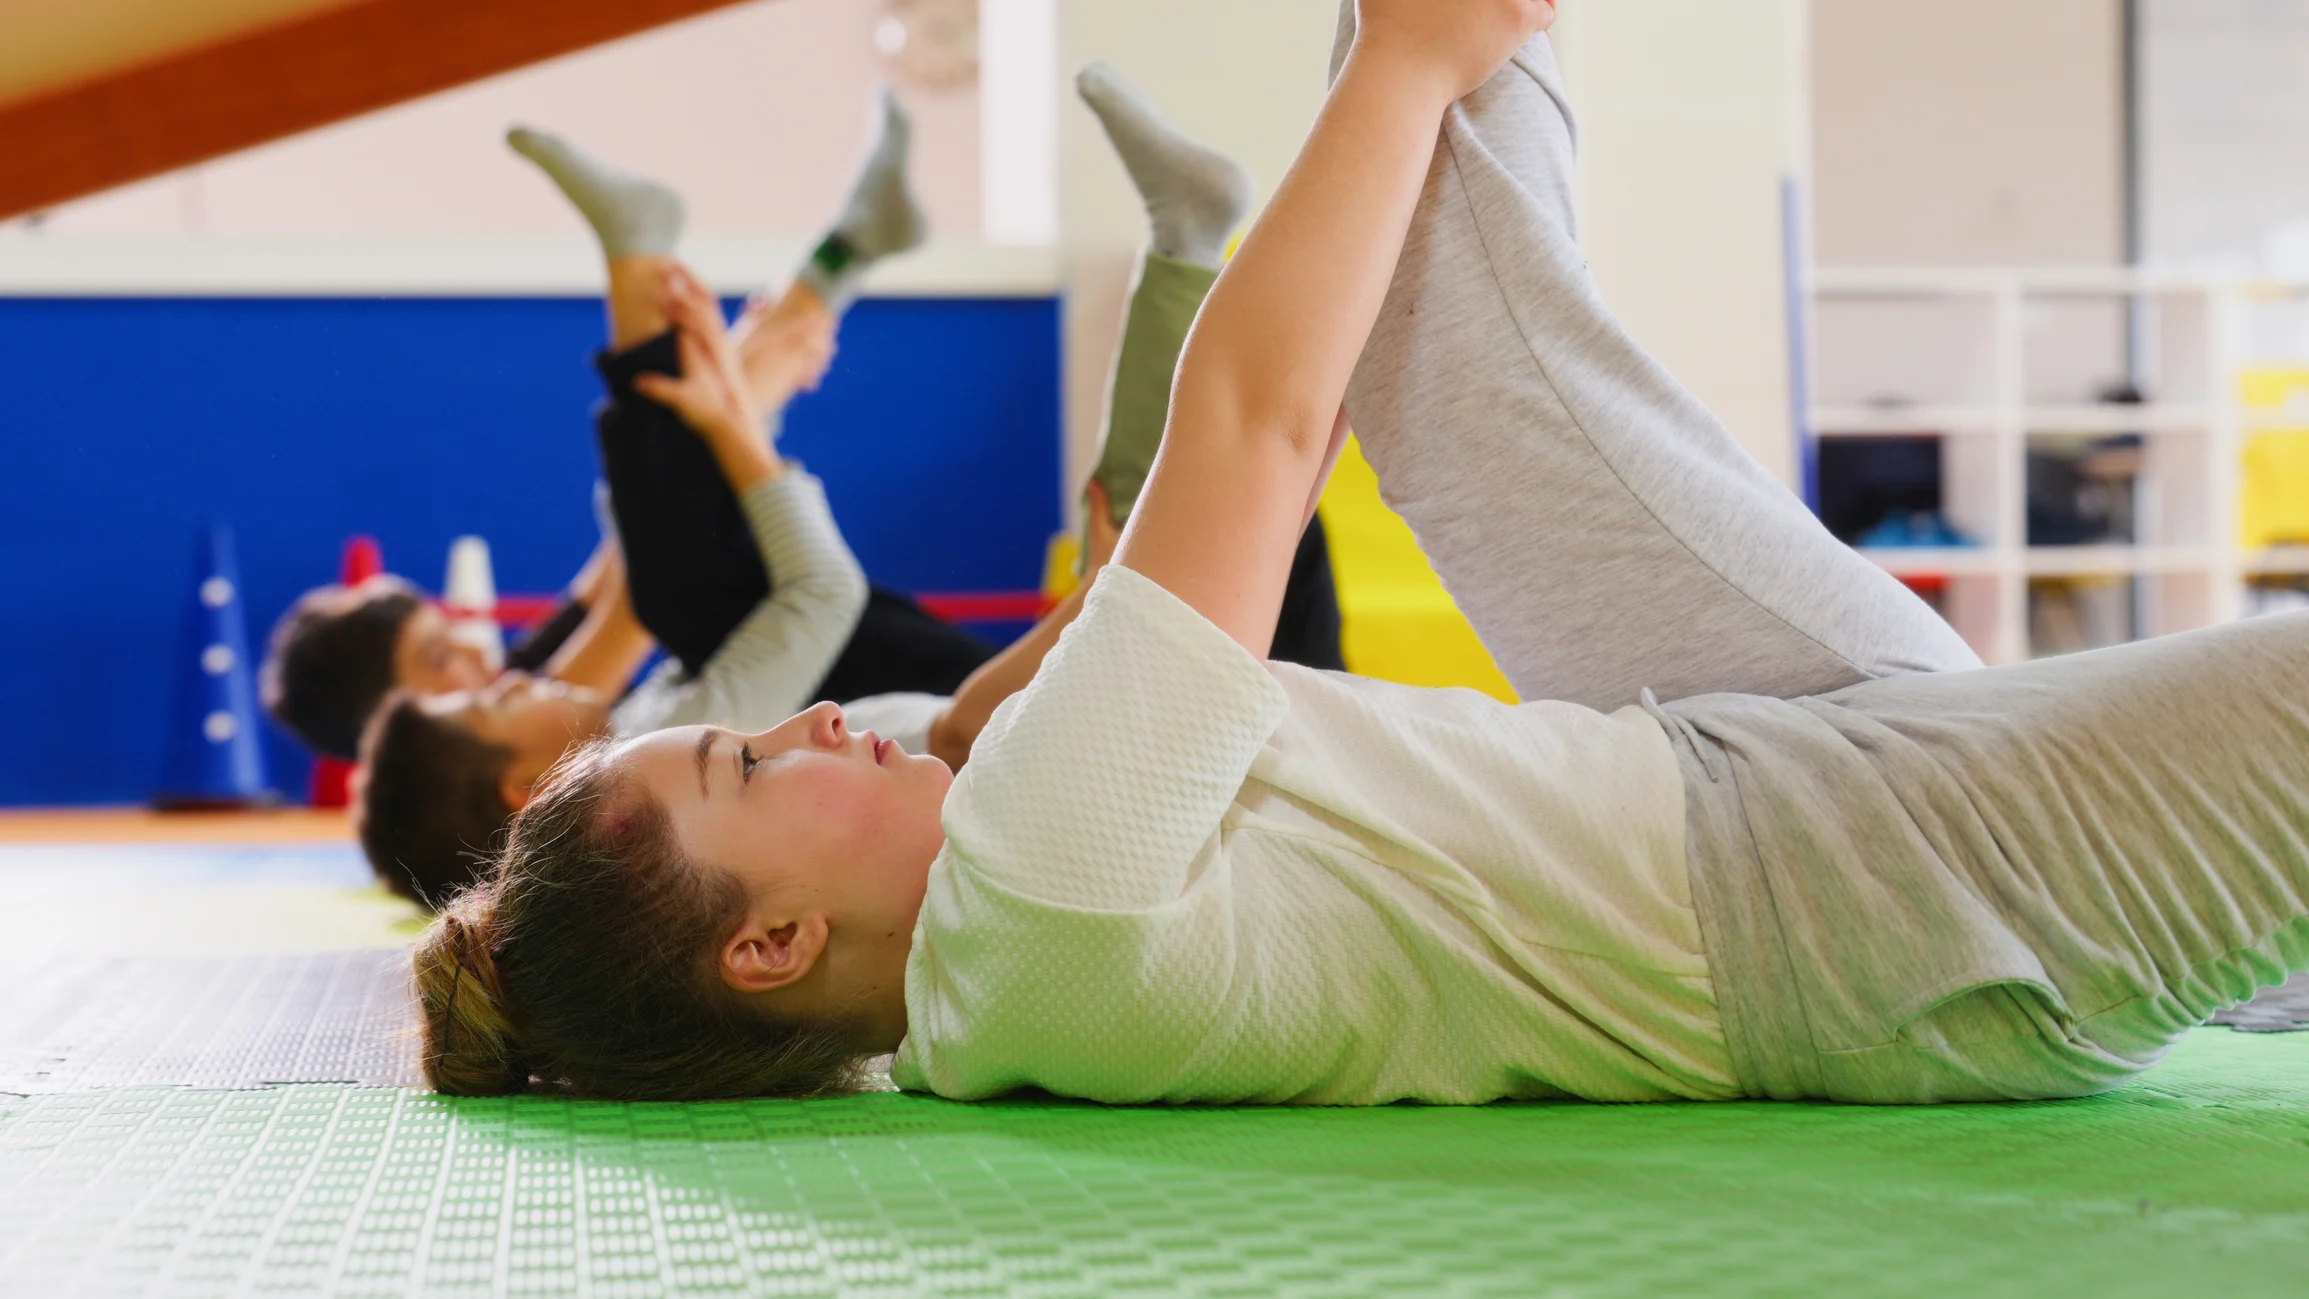
For extracurricular sporting activities the mechanism changes. Regard children between 5 and 18 years old and allows you to deduct 19% of expenses incurred for registrations and subscriptions to gyms, swimming pools and amateur sports associations, up to a maximum of 210 euros per year per child: the actual saving, therefore, stops at around 40 euros each. The ceiling is per child, not per parent, and does not change even if the child plays multiple sports together: the maximum allowable expense always remains the same. Anyone who turns 18 during the year does not lose the right to the deduction, which is valid for the entire tax period. But it is not enough to enroll your child in any sporting activity to be entitled to the bonus: the discipline practiced in itself makes no difference, football, swimming, dance, martial arts, volleyball or gymnastics are all fine. What matters is who organizes the course. The deduction is only applicable if the registration is made at amateur sports associations (ASD or SSD) recognized by Coni or by the respective national sports federations, or at gyms and swimming pools that host courses managed by these bodies. A private course held by an instructor not connected to a recognized sports club, or a general gym membership without an amateur association behind it, does not entitle you to the benefit. And those incurred for sports clothing, shoes and equipment are excluded from the deductible expenses.
Music courses: bonus up to 190 euros, but with an income limit
There are also deductions for music courses. The maximum limit is one thousand euros, but the difference lies in an economic constraint that the other items do not have: the benefit is only available to families with a total income that does not exceed 36 thousand euros a year. Once this threshold is exceeded, the music bonus can no longer be used, regardless of the ISEE of the family unit, which in this case does not count. Courses held by conservatories, institutes of higher musical education, music schools registered in regional registers, choirs, bands and academies recognized by a public body are eligible. If more than one child in the family follows music courses, the deduction applies to each of them, calculated separately. And if the expense is divided between the two parents, the limit of one thousand euros still remains unique for each child, to be divided between those who actually paid.
The detail that causes the deduction to be missed: how to pay and what to keep
There is a rule that always applies to being able to deduct children’s tuition in your tax return: payment in cash completely loses the right to deduct. To report these expenses you must pay with traceable instruments, such as bank or postal transfer, debit or credit card, debit card or postal order. It is then fundamental keep the documentation carefully: receipts, invoices or receipts must clearly show the data of the enrolled child and the tax code of the person who paid, the data of the person who collected the payment (name and headquarters, or name and residence if it is a natural person), the relevant tax code, the reason for the payment, the activity carried out, the amount. For school expenses not organized directly by the institute, a copy of the school resolution is also required. Then there are the overall income limits to consider. Those who exceed 120 thousand euros in income see the deduction gradually decrease, until above 240 thousand euros there is nothing left to recover. Paying attention, therefore, to the payment method and immediately asking for a complete receipt can make the difference between recovering a few dozen euros or losing them forever.